
Textron surged 5.3% in pre-open trading after releasing third-quarter results that topped expectations. The aerospace and defense manufacturer reported adjusted earnings per share of $1.76, versus a Wall Street consensus of $1.43, producing a clear earnings upside that prompted the rally ahead of the market open.
Revenue for the quarter totaled $3.8 billion, roughly 4% higher year-over-year and modestly above the $3.77 billion estimate. Manufacturing cash flow rose materially to $512 million, compared with $348 million in the same quarter a year earlier, providing a cash-flow backdrop to the stronger operating print.
Management also raised its full-year 2026 adjusted EPS guidance to a range of $6.55 to $6.65. The midpoint of that range - $6.60 - sits above the prior analyst consensus of $6.47. In addition, Textron lifted its cash flow outlook to a range of $800 million to $900 million, giving further weight to the company's updated financial trajectory.
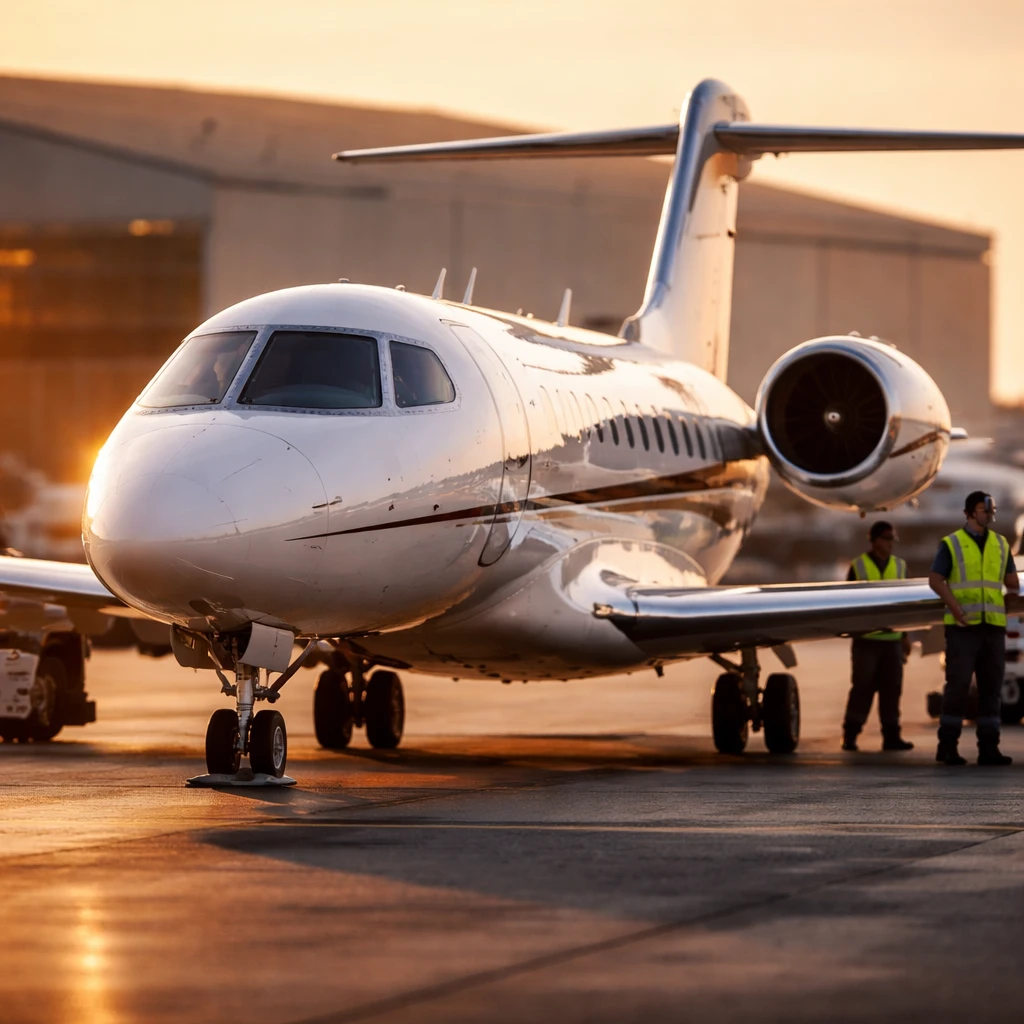
The Aviation segment was the most notable contributor, with revenue climbing 14% to $1.7 billion. That top-line strength was supported by a 21% increase in Citation jet deliveries, a figure highlighted by management in the quarter's disclosure.
Capital allocation moves accompanied the operating results. During the quarter, Textron repurchased $239 million of its common shares, an action management framed as a vote of confidence in its stock at current pricing levels.
Analyst sentiment heading into the quarter had been cautious; several firms, including Morgan Stanley and Citi, had trimmed price targets. Those lowered expectations created a comparative low bar that the actual results exceeded.
The broader market did not aid Textron's move. At the time of the pre-market rally, the S&P 500 was down 0.4%, the Dow Jones Industrial Average fell 0.2%, and the Nasdaq slid 1.2%. Disappointing earnings from major technology companies and renewed concerns about the return on investments related to artificial intelligence pressured equity benchmarks, yet Textron managed to rally amid those headwinds.
Industrial and defense sector performance was mixed across the trading session, underscoring that Textron's uptick was driven by company-specific results rather than broad market momentum. The stock pushed toward $82.50 in pre-market action, trading well above its 52-week low of $71.87.
Taken together, the sizable earnings beat, the upgraded full-year outlook, stronger Aviation execution and targeted share repurchases gave investors distinct catalysts to re-evaluate the stock's valuation. Those elements combined to produce the notable pre-open move despite macro and sector-level pressures.
Clear summary
Textron reported stronger-than-expected third-quarter results, raised its 2026 adjusted EPS and cash flow guidance, and executed $239 million in share repurchases. The Aviation segment led revenue growth, and the stock rallied 5.3% in pre-market trading even as major indices slipped.