
Market move and analyst action
J.P. Morgan moved CSG from an "overweight" rating to "neutral" and lowered its price target by 54% to €12 from €27.50 following the company's surprise downward revision to its 2026 profit and free cash flow guidance announced on Nov. 11. The stock closed at €10.70 that day and has declined roughly 40% over the prior three months.
Why the downgrade
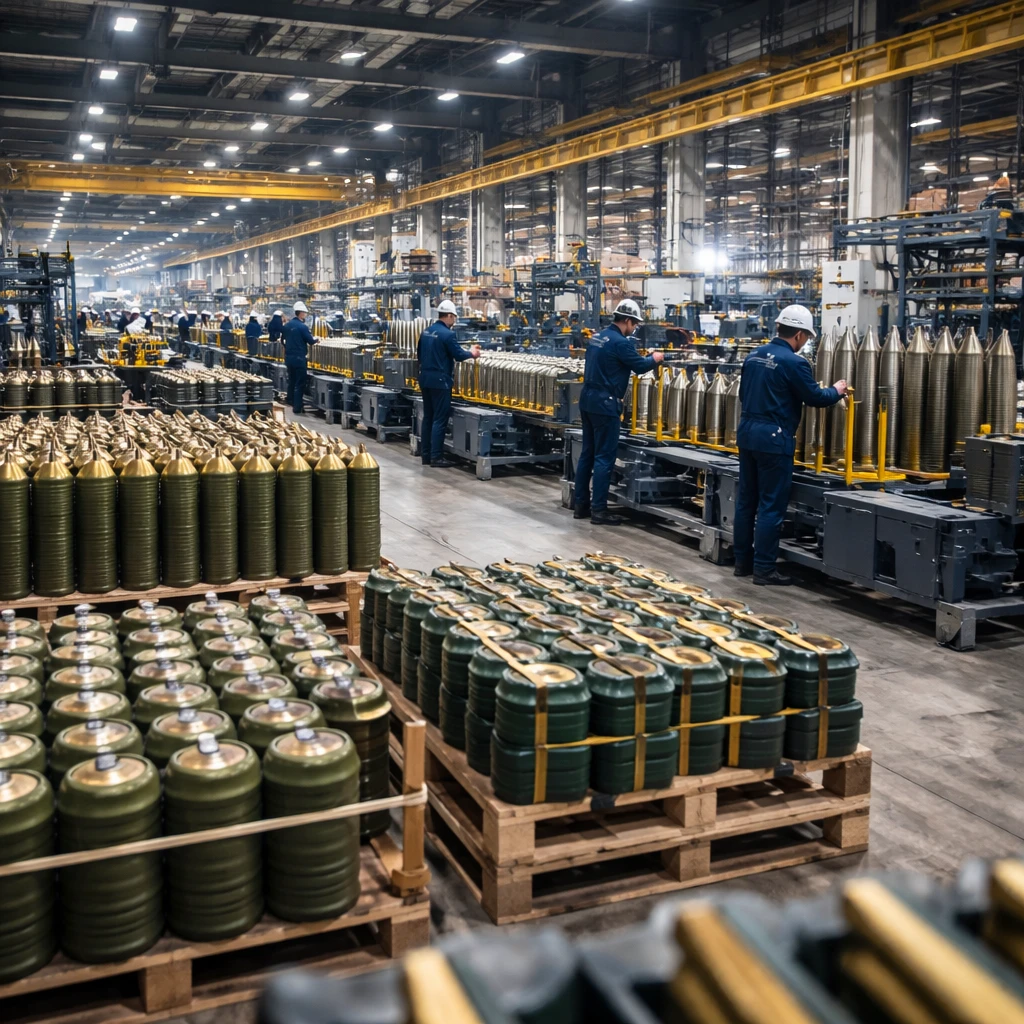
The brokerage pointed to mounting evidence that earnings from medium and large-calibre ammunition may be materially lower than had been anticipated at the start of the year. Analyst David Perry highlighted two structural and market developments behind that view: a change in battlefield demand as drones alter warfare dynamics, and government buyers pressing for improved value while CSG and competitor Rheinmetall expand production capacity. Together, these factors have increased the risk of lower profitability in key ammunition segments.
Orders, sales and margin details
Data from the Kiehl Institute cited by J.P. Morgan indicate Ukraine purchased minimal ammunition between February and August 2026, and CSG has not announced significant medium or large-calibre orders since April 2026. Those developments are reflected in CSG's third-quarter results, which fell short of consensus.
Q3 sales were €1.51 billion, beneath the Bloomberg median estimate of €1.87 billion, while adjusted EBIT came in at €317 million compared with an expected €461 million. The miss was driven primarily by medium and large-calibre ammunition, where customers shifted preferences toward long-range artillery rounds rather than standard-range ammunition. That left the company with inventories of short-range rounds that were sold at discounted prices. As a result, the adjusted EBIT margin declined to 21.0% from 23.5% a year earlier.
Order intake and book-to-bill
New orders during the quarter totaled €900 million, producing a book-to-bill ratio of 0.6 times, a level that signals order intake materially lagging shipments for the period.
Updated 2026 targets
CSG kept its top-line sales guidance for 2026 unchanged at €7.40 billion to €7.60 billion, but trimmed its adjusted EBIT margin target to 21% from a prior range of 24% to 25%. J.P. Morgan interpreted the revised guidance as implying a margin of about 20% for medium and large-calibre ammunition in the fourth quarter, down from roughly 30% in the first nine months of the year.
Cash flow, working capital and debt implications
Reflecting the weaker margin outlook, higher working capital and supplier financing, J.P. Morgan reduced its 2026 free cash flow forecast for CSG to negative €695 million from a prior projection of €860 million. The brokerage attributed the downgrade to the lower adjusted EBIT, a shift in working capital guidance and approximately €700 million in loans extended by CSG to its suppliers. CSG itself now expects net working capital at the end of 2026 to be below 35% of revenue, compared with its earlier guidance of below 20%.
J.P. Morgan included the supplier loans in its free cash flow calculation; it noted that if those loans were reported below free cash flow, the bank's 2026 free cash flow estimate would be nearer breakeven.
On a balance-sheet basis, the brokerage now forecasts net debt of €3.6 billion in 2026, versus its earlier estimate of €1.8 billion. The rise largely reflects lower projected cash generation and CSG's roughly €400 million investment in MDA Space.
Earnings per share outlook
J.P. Morgan lowered its 2026 earnings per share forecast for CSG to €0.92 from €1.15.
The firm's revised view centers on a deterioration in profitability for medium and large-calibre ammunition driven by a changing demand mix, inventory markdowns on short-range rounds, slower order intake and increased working capital and supplier financing needs.